
Clean Yield Speaks Up to Protect Shareholder Advocacy


Our Public Comment on the Proposed Rescission of the Shareholder Resolution Process
By Liz Levy, Managing Director and Portfolio Manager
Shareholder advocacy and engagement are an essential part of Clean Yield’s work to help our clients make a positive impact on the world. As part of our commitment to responsible investing on behalf of our clients, Clean Yield actively engages with companies we invest in to encourage better environmental, social, and governance practices. Through our shareholder advocacy, Clean Yield leverages our position as an investor to initiate and engage in dialogues with corporate management, and file shareholder resolutions when appropriate.
Over the course of the last two years, we have been following the proposed rule changes by the U.S. Securities and Exchange Commission (SEC) that would eliminate the ability for investors to include proposals on a company’s proxy statement for vote at annual meetings. On September 16, 2026, the SEC proposed the Rescission of Rule 14a-8’s Federal Regulation of Shareholder Proposals and Amendments to Rule 14a-4, with a 60-day public comment period open until November 20, 2026.
What Does the Proposal Mean
As explained by the Shareholder Rights group, of which Clean Yield is a member: “… the SEC is proposing to rescind its shareholder proposal rule, a more than 80-year-old process that lets shareholders engage with fellow shareholders and their portfolio companies. For retirees and retail investors whose savings are invested in public companies, the federally regulated shareholder proposal process is one of the few direct tools available to ensure effective risk management and corporate governance. For decades, shareholders have relied on this right to bring important issues to fellow investors for a vote. Shareholder proposals have held boards accountable by requiring that they receive a majority vote to remain on the board. Other proposals have pushed companies to address climate-related financial risks that could pose significant liabilities in the future. Proposals have addressed excessive executive pay and other abuses of power. Recently, proposals have sought transparency on risks related to companies’ deployment of Artificial Intelligence.”
Our clients choose to work with Clean Yield to manage their investment portfolios because we allow them to align their portfolios with their values while meeting their financial goals. We rely on the mechanisms of the shareholder resolution process to enhance our dialogues with companies and to demonstrate our views as company owners to companies with which we are not engaged, via proxy voting on resolutions other investors have filed. We view both activities, engagement and voting, as part of our fiduciary duty to our clients — not separate from it.
Therefore, Clean Yield has submitted a public letter opposing the rescission of Rule 14a-8 and amendments to Rule 14a-4, urging the withdrawal of the proposed rescission and amendments.
📝 Read the full text of our comment letter.
💭 You can see all the publicly submitted comments on the SEC website.
Sign up to our newsletter to stay informed about shareholder advocacy news and updates.
We are always looking for ways to maximize the positive impact our clients’ assets can make in the world, whether through proxy voting, shareholder activism, or impact investing. We share our latest updates on these topics in our newsletter.
Why Clean Yield Is Opposed
In addition to our reliance on the shareholder resolution process established by Rule 14a-8 to meet our fiduciary duties to our clients, our opposition to the rule’s rescission hinges on several factors:
- Voting is our right as equity owners, as compensation for risk of ownership: Our
rights as shareholders come from the fact that collectively as equity investors, we are the
owners of the companies we invest in. If a company goes bankrupt, its creditors —
including bondholders that have loaned the company money in anticipation of being paid
back a set amount — get made whole first. Equity investors, such as Clean Yield’s
clients who own the stock of the company, get whatever is left over, if anything. In return
for that extra risk, we have the right to have a say in the governance of the company, as
owners. While we believe there is value to the company in learning of equity owners’
support level of shareholder proposed resolutions, we also believe that it is our right to
vote on them. - Other alternatives to raising issues for a vote are cost-prohibitive: Alternative
methods for having issues raised at Annual Meetings, such as independent solicitations
or presenting floor resolutions, are not affordable for small investors to undertake.
Particularly with the proposed amendments to the 14a-4 process, the cost of conducting
an independent solicitation would be far, far greater than filing a shareholder resolution
under either the current 14a-8 or 14a-4 processes. - We would be unable to fulfill our fiduciary duty: Under proposed amendments to the
14a-4 process, a company’s proxy card would contain a single checkbox either giving or
denying the company discretion over voting our clients’ shares with regards to all
non-14a-8 shareholder proposals that are not listed on the card. We would be limited
either granting discretionary voting authority for all of the proposals or none to the
company. These amendments would prevent us from using our own discretion on our
clients’ behalf, as they have hired us to do. - Investors need to be able to express our opinion to companies via voting: Without
the ability to raise specific issues for vote at the Annual Meeting via shareholder
proposals, and without the ability to know what issues other investors have concerns
about, investors are left with very few ways to communicate concern to a company of
which they own shares. Under the proposed rescission, without the ability to assess how
the wider pool of investors feels about particular issues, companies would be left without
input that could be helpful to them.
Learn more about our approach to shareholder advocacy and proxy voting and reach out if you’d like to learn more about our client services.
Liz Levy is responsible for researching publicly traded equities and managing client portfolios, having joined Clean Yield in June 2024. She brings more than 20 years of experience in Sustainable Investing. She is a Chartered Financial Analyst and is passionate about aligning investment portfolios with values, with deep experience in managing divested, fossil fuel-free, and clean energy investments.
More News & Insights
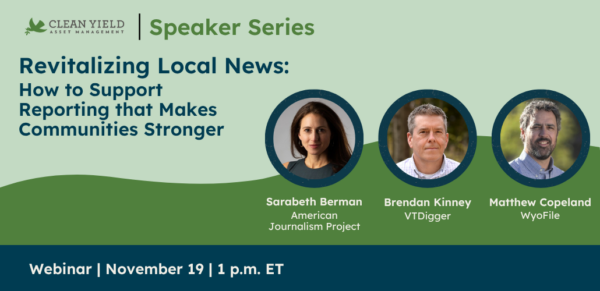
Speaker Series — Revitalizing Local News: How to Support Reporting that Makes Communities Stronger
Independent local journalism is essential to a functioning democracy. Join this webinar to learn how we can support stronger communities through revitalizing local independent newsrooms.
How to Align Philanthropy and Donations with Your Financial Goals
Charitable giving from your investment portfolio could be a smart way for you to support the charities and causes you care about.
Q3 2026 Market Outlook: Weathering the Interest Rate Storm
Our team’s reflections on Q3 2026 and what to expect in the coming months from the market, inflation, bonds, investing, and more.
